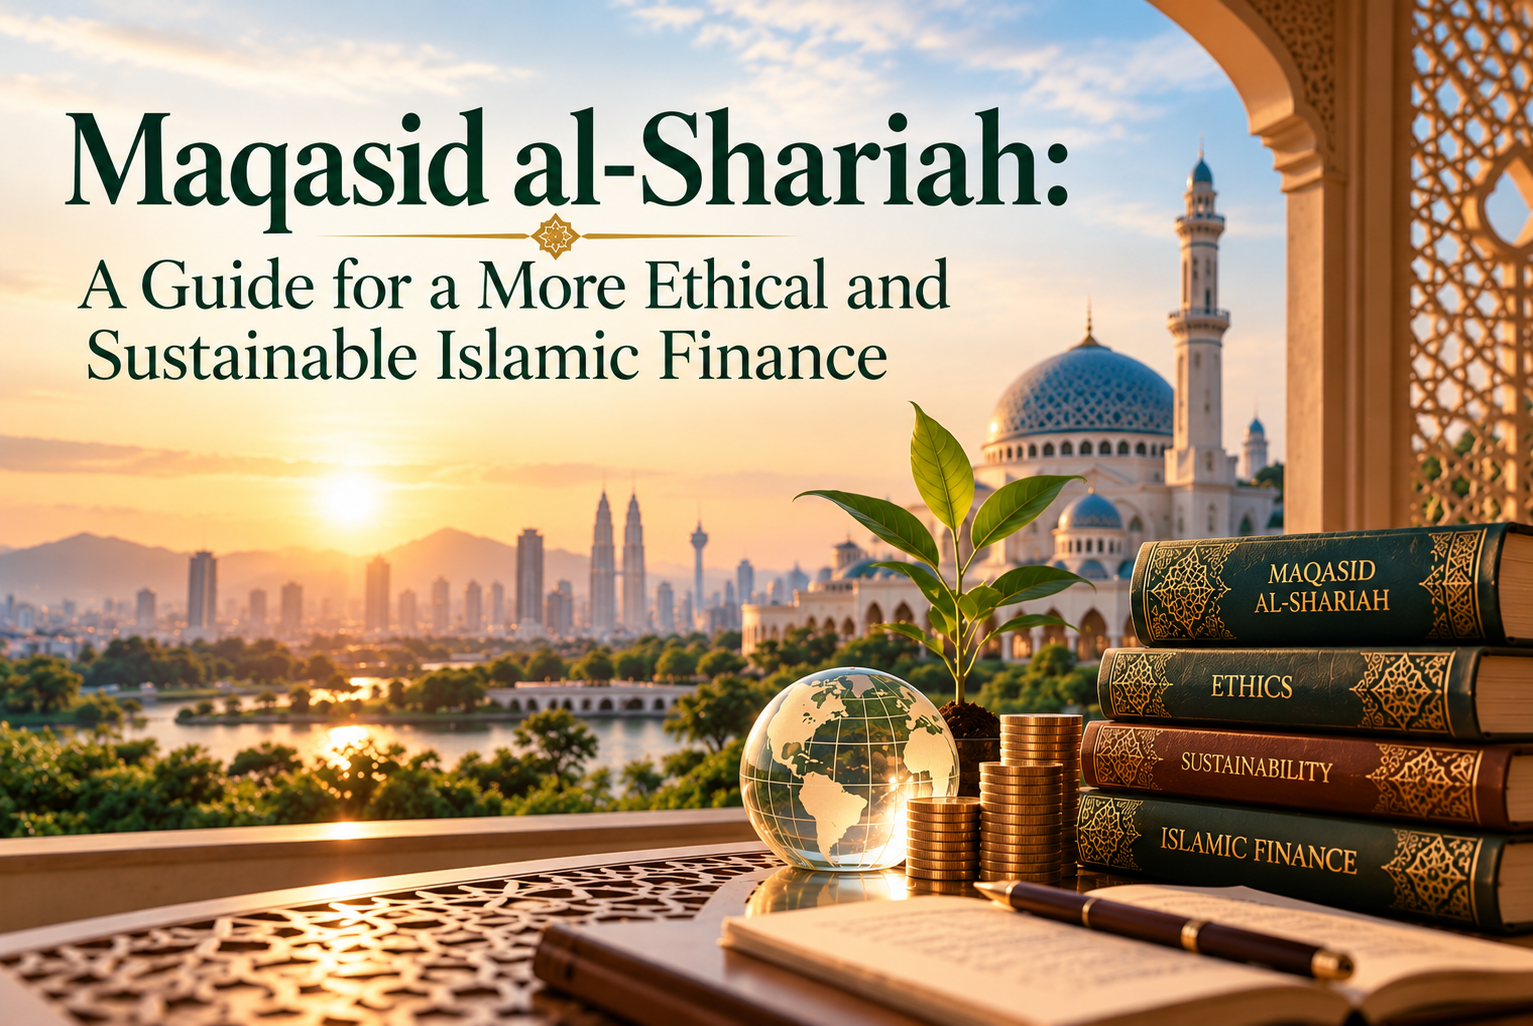
Maqasid al-Shariah: A Guide for a More Ethical and Sustainable Islamic Finance
Islamic finance is often understood through its most familiar principles: the prohibition of riba (interest or usury), avoidance of excessive gharar (uncertainty), and prohibition of maysir (gambling or speculation resembling games of chance).
These principles are fundamental, but Islamic finance is about more than avoiding prohibited activities. At its heart is a broader objective: creating an economic and financial system that promotes justice, responsibility, transparency and human well-being.
This is where Maqasid al-Shariah, or the higher objectives of Shariah, becomes especially important.
What is Maqasid al-Shariah?
Maqasid al-Shariah refers to the higher purposes and objectives that Islamic law seeks to achieve.
Classical Islamic scholarship commonly discusses the protection and advancement of five essential interests:
- Faith (Din) – protecting religious belief and practice.
- Life (Nafs) – protecting human life, dignity and well-being.
- Intellect (‘Aql) – protecting knowledge, reasoning and intellectual development.
- Lineage and Family (Nasl) – protecting family, future generations and social stability.
- Wealth (Mal) – protecting property and ensuring wealth is acquired and used responsibly.
Together, these objectives provide a broader ethical framework for understanding how Islamic principles should contribute to society.
In finance, this means asking not only whether a transaction is technically permissible, but also whether it produces a fair, responsible and beneficial outcome.
Beyond Shariah Compliance
A financial product may be structured to satisfy contractual Shariah requirements. However, Maqasid encourages us to consider a deeper question:
What is the actual economic and social outcome of the transaction?
For example, financing should ideally support productive economic activity rather than exploitation. Investment should create value rather than merely transfer risk unfairly from one party to another.
Transparency should enable participants to understand their obligations, risks and rights.
This distinction is important. Islamic finance should not simply reproduce conventional financial products using different terminology. Its principles offer an opportunity to develop financial systems in which ethics and economic activity operate together.
Justice and Fairness in Financial Transactions
Justice is one of the central values associated with Islamic economic thought.
A healthy financial system should avoid situations where one party receives excessive benefit while another carries disproportionate risk.
Islamic financial structures therefore emphasize concepts such as contractual clarity, ownership, accountability and appropriate risk-sharing.
In arrangements such as Musharakah and Mudarabah, for example, the relationship between capital, entrepreneurship, profit and risk can be structured around partnership rather than a simple lender-borrower relationship.
The objective is not to eliminate commercial profit. Islam recognizes legitimate trade and investment.
Rather, wealth should be generated through lawful and productive economic activity while respecting the rights of everyone involved.
Connecting Finance to the Real Economy
Another important aspect of Islamic finance is its connection with real economic activity.
Structures such as Murabahah, Ijarah, Musharakah, Mudarabah and Sukuk generally involve identifiable assets, services, businesses or economic activities.
This connection can encourage finance to serve the real economy.
Capital can be directed toward businesses, infrastructure, housing, education, healthcare, agriculture, technology and other productive sectors that contribute to society.
From a Maqasid perspective, the question becomes:
How can finance create sustainable value for people rather than becoming an end in itself?
Financial Inclusion and Social Responsibility
Maqasid al-Shariah also provides a framework for thinking about financial inclusion.
A financial system should not serve only institutions and individuals who already possess substantial wealth.
Islamic economic principles include mechanisms such as Zakat, Waqf, Sadaqah and Qard Hasan, which demonstrate the importance placed on social welfare, redistribution and community support.
Modern Islamic finance can build upon these principles by developing solutions for underserved communities, small businesses, entrepreneurs and individuals who may have limited access to conventional financial services.
Technology can potentially expand this reach further.
Digital platforms, mobile payments, responsible fintech and other innovations can reduce barriers to financial participation—provided that technology remains guided by appropriate ethical, legal and Shariah considerations.
Maqasid and Sustainable Investment
There is also growing interest in the relationship between Islamic finance and sustainable development.
Environmental responsibility, ethical investment, responsible business practices and long-term economic sustainability can be considered alongside traditional Shariah requirements.
A Maqasid-oriented approach encourages investors and financial institutions to examine where capital is being deployed and what impact that investment creates.
Investment decisions can therefore consider not only financial returns but also wider consequences for communities, future generations and the environment.
This does not mean that every investment must become charitable.
Commercial investment must remain economically viable. The challenge is to find a balance between profitability, responsibility and beneficial impact.
The Role of Technology
Technology is transforming the global financial system.
Artificial intelligence, blockchain, digital assets, smart contracts and automated compliance systems are creating new possibilities for how financial products are structured and delivered.
For Islamic finance, these technologies present both opportunities and important questions.
Technology can improve transparency, reduce administrative costs, automate contractual obligations and expand access to financial services.
However, technological innovation alone does not make a financial product ethical or Shariah-compliant.
The same fundamental questions remain:
Is the transaction fair? Is ownership clear? Are the risks understood? Is there excessive uncertainty? Does the structure involve prohibited activities? Does it create genuine economic value?
Innovation should therefore serve the objectives of Shariah rather than allowing technology to become the objective itself.
Towards a More Purpose-Driven Islamic Finance
The future of Islamic finance should not be measured solely by the size of its assets or the number of financial products available.
Its success should also be measured by the quality of the economic outcomes it produces.
- Can Islamic finance support entrepreneurship?
- Can it contribute to infrastructure and development?
- Can it improve financial inclusion?
- Can it encourage responsible investment?
- Can it protect investors while allowing businesses to obtain capital?
- Can it use technology without abandoning ethical principles?
These questions bring Islamic finance back to its underlying purpose.
Maqasid al-Shariah reminds us that rules, contracts and financial structures exist within a larger moral and social framework.
Islamic finance, when guided by these objectives, has the potential to be more than an alternative financial system. It can contribute toward a financial ecosystem in which commerce, ethics, innovation and social responsibility reinforce one another.